Condemnation Claims | How to Handle Insurance & Property Rights
Ever wonder what happens if the government or another authority takes your property for public use? Maybe you’ve heard terms like “eminent domain” or “condemnation” but aren’t sure what they mean for you as a property owner. Learning about condemnation claims and your insurance options can make a big difference if you ever get that official-looking letter. Here’s what you need to know, simply explained.
What Is Condemnation?
Condemnation is the legal process where a government or sometimes a utility company takes private property for a public project. This might mean building a new highway, school, or utility line. The law usually requires the property owner to get paid for the property taken, but the process is rarely simple.
A common misconception is that condemnation always means a building is declared unsafe or unlivable. That’s just one type. In property law, condemnation is about the government’s right to take private land for public use, this is called eminent domain. Sometimes, only a slice of your land is taken, or access to your property is limited, even if your house stays right where it is. Changes like these can have a real effect on how you use and enjoy your property.
Picture this: The city wants to widen the street and needs a piece of your front yard. Or maybe a new bike path is planned, and the county needs part of your backyard. Even if you keep most of your property, these takings can impact your daily life and your property’s value.
Why Does Condemnation Happen?
The most common reason for condemnation is “public use.” This covers things like highways, schools, parks, or utilities such as pipelines and power lines. Local, state, or federal government agencies, and sometimes private companies working with the government, can use this power. They’re supposed to offer “just compensation,” meaning a fair market value for what’s taken. But fair is often in the eye of the beholder.
Sometimes, condemnation happens for health or safety reasons. For example, if a building is so damaged it’s dangerous, the city might “condemn” it and force you to leave. This is different from taking land for a road or park, but the process still involves official notices and, sometimes, a fight over money.
There are also cases where only part of a property is needed. This is called a “partial taking.” Maybe only the piece at the back of a lot is needed for a drainage ditch. Even if the main building isn’t touched, the loss can affect how you use the property, which can lower its value or make it less convenient.
Understanding Condemnation Claims
A condemnation claim is when you push back against the government’s attempt to take your property, or you challenge the amount you’re offered. You might file a claim if you think the offer is too low, believe the process wasn’t fair, or question whether the taking is truly necessary for public use.
You have rights during condemnation, including:
- Getting written notice about what’s being taken and why.
- The right to negotiate or challenge the offer, sometimes in court.
- The right to hire your own appraiser to give an independent estimate of your property’s value.
- In some cases, the right to recover legal costs if you win your challenge.
Compensation isn’t just about the land’s sale price. If the taking affects how you use the rest of your property, like if you lose parking, a driveway, or access to a street, you might be entitled to extra compensation. For example, if a new highway cuts through your backyard and leaves you with less usable space, or makes it harder to get to your house, that loss should be considered.
The Insurance Claims Process After Condemnation
Where does insurance fit in? Can you make an insurance claim if your property is condemned? The answer is: it depends, mostly on your policy and the reason for condemnation.
Most standard homeowners or commercial property insurance does not cover losses from government action, including condemnation. Insurance companies typically exclude government takings from policies, so if the city wants your land for a new park, you usually can’t file a claim under your regular policy.
There are exceptions. Some specialized policies, called eminent domain insurance or condemnation insurance, may offer limited protection. These are rare for homeowners but sometimes used by businesses or investors with large or vulnerable properties. If you own a shopping center near a planned freeway, for example, this insurance might help cover gaps between the government’s offer and what you think the property is worth.
If you have a mortgage, your lender might require you to carry insurance that includes some protection against condemnation, especially on commercial properties. In those cases, insurance could help pay off the loan if the property is taken, but the coverage is usually designed to protect the lender, not you.
Here’s a key point: If your property is damaged by something like fire or flooding, and then condemned because it’s unsafe, your regular insurance may cover the damage (like repairs or rebuilding), but not the government action itself. If the government wants your land for a new transit line, though, that’s a separate matter and rarely covered.
Steps to Take If Your Property Faces Condemnation
If you receive a condemnation notice, don’t panic, but don’t ignore it, either. Here’s what you should do:
- Read the notice closely. It should spell out exactly what part of your property is being taken and why.
- Contact a lawyer who handles condemnation cases. They can walk you through your rights and help you respond properly.
- Get your own appraisal from a qualified professional. Don’t rely only on the government’s number, independent appraisals often come in higher.
- Review your insurance policies. While most won’t help with government takings, check for any endorsements or special coverage you might have.
- Respond by the deadline. Timeframes for challenging a condemnation or negotiating a better offer can be short.
- Gather paperwork, such as deeds, surveys, and evidence of how you use your property. This can help support your claim for fair compensation.
Missing a deadline or failing to provide important documents could limit your rights or reduce your chances of getting a better offer.
How Eminent Domain Insurance Works
Eminent domain insurance is a special type of policy meant for situations where the government takes private property. It’s uncommon for homeowners but can be valuable for commercial property owners, investors, or developers with land that’s at risk.
Here’s how it generally works:
- The policy may cover the difference between the government’s offer and the actual fair market value, based on an independent appraisal.
- Some policies will also help pay for legal expenses if you need to fight the condemnation in court.
- There may be limits on the types of takings covered. For instance, some policies only apply if a certain percentage of the property is taken, or if the taking is for a specific public use.
- Payouts are often capped, and policies may have strict requirements about documenting your loss.
Eminent domain insurance isn’t cheap, and the fine print matters. For example, coverage may be denied if you didn’t notify the insurer quickly enough, if the taking was foreseeable when you bought the property, or if the government’s offer is close to your own appraised value. Always read the policy carefully and talk to an experienced insurance agent or attorney before buying.
Let’s say you own a warehouse on the edge of an expanding city. You suspect your land might be needed for a new light rail stop in the next few years. Eminent domain insurance could give you peace of mind, knowing you’ll have help if the government’s offer isn’t enough or if you need to pay for legal help to negotiate a better deal.
Property Rights Claims: What Are Your Options?
When your property is threatened by condemnation, you aren’t powerless. Here are the paths you can take:
- Accept the government’s offer if you believe it’s fair. This is the fastest route but might not be best if you think the offer is low.
- Negotiate for more money. Many agencies expect some negotiation, and a higher offer may be possible if you have good evidence.
- File a formal condemnation claim or lawsuit. This gets the courts involved and can lead to better compensation, but it can take time and may require expert witnesses and legal help.
- Challenge whether the taking is truly for public use. If you believe the project serves private interests or isn’t necessary, you can fight the taking itself. These challenges are tough but not impossible, especially if the public benefit is unclear.
Acting quickly is critical. If you wait too long, you could lose your chance to negotiate or challenge the process. Deadlines vary by state and can be as short as a few weeks.
Say your city wants part of your land for a new playground. You get an offer that seems low, so you hire an appraiser who values your property much higher. With this evidence, you negotiate and get a better payout. Or, if you’re convinced the project isn’t really public (maybe it’s for a private developer), you and your lawyer could challenge the taking in court. Both paths require careful planning and good documentation.
The Role of Appraisals and Expert Help
Appraisals are central to any condemnation claim. The government will usually hire its own appraiser, but their job is to serve the agency, not you. Hiring your own appraiser gives you a second opinion and often uncovers details that can boost your claim.
A professional appraiser looks at recent sales, the unique features of your property, and how the taking will affect what’s left behind. For example, if you lose parking spaces or if the remaining land becomes hard to use or sell, a good appraiser will document that impact.
You may also need other experts. Engineers can explain how the loss of land affects drainage or access. Real estate consultants can estimate how hard it will be to sell what’s left. These experts add weight to your case, especially in court.
Working with a lawyer who specializes in condemnation law is a smart move. They’ll know the local rules, common tactics used by government agencies, and can help coordinate appraisals, negotiate offers, and file formal claims if needed. Lawyers can also spot errors in the process, like missing notices or rushed deadlines, that could help your case.
Common Pitfalls in Condemnation and Insurance Claims
The condemnation process can be confusing and stressful. Many people make mistakes that hurt their chances of fair compensation. Here are some of the most common pitfalls:
- Accepting the first offer without question. The initial offer is often negotiable, and agencies expect you to push back if you have evidence.
- Waiting too long to respond. Deadlines are strict, and missing one can shut down your options.
- Not getting your own appraisal or expert help. Relying on the government’s estimates rarely gets you the best result.
- Overlooking the impact on the rest of your property. Sometimes, the loss isn’t obvious until you consider things like lost income, access, or future development potential.
- Assuming your standard insurance will cover you. Most policies exclude losses from government action, so double-check before counting on an insurance payout.
- Not documenting your property’s use or improvements. Take photos, save receipts, and gather any paperwork that shows how you use and maintain your land.
- Ignoring the emotional impact. Losing part of your property can be upsetting, but decisions should be based on facts and expert advice, not just frustration.
[Inline Image Placeholder]
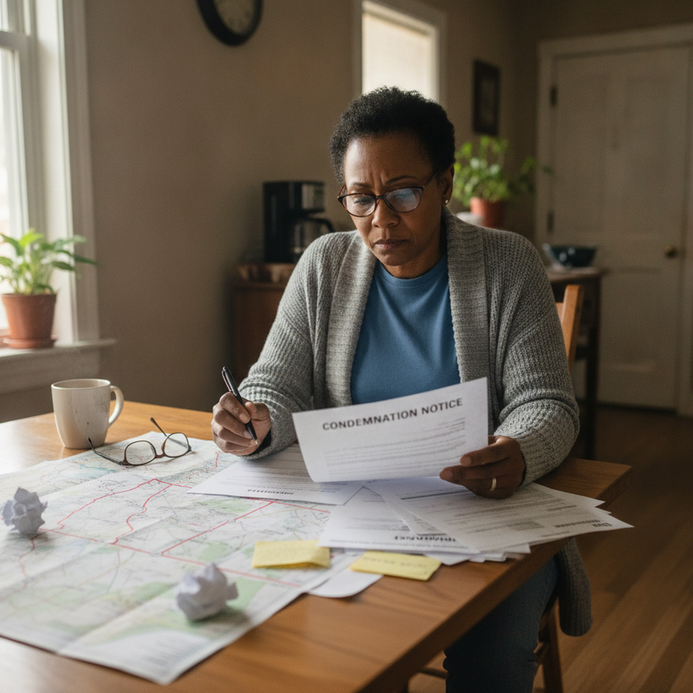
alt text: “A worried homeowner reviewing a government condemnation notice at their kitchen table, with a property map and insurance papers spread out.”
prompt: “A middle-aged homeowner sitting at a kitchen table, looking worried, with a condemnation notice and property map spread out, insurance documents visible, realistic style”
Real-Life Example: How Condemnation Claims Work
Let’s walk through a real-world scenario to see how all these pieces fit together. Imagine your city plans to widen the main road in front of your house. You get a letter saying they need five feet of your front yard for the project. The city’s offer seems low, and you’re not sure what to do next.
- You read the notice carefully and see that you have 30 days to respond.
- You hire a local appraiser, who determines that the city’s offer is $10,000 below the actual value of the land, especially considering how the loss of yard space will impact your property’s curb appeal and resale value.
- You contact a lawyer who specializes in condemnation cases. The lawyer reviews your appraisal, the city’s plans, and helps you draft a formal response.
- You try to negotiate with the city, sharing your appraisal and explaining the impact on your property. The city increases its offer, but it’s still not quite fair.
Received a condemnation payment?
Get a free, no-obligation review of the tax treatment before you file.
Get a Free Tax Review